The mortgage loan application process starts with pre-qualification and ends at the closing table, typically spanning 30 to 45 days. During this time, lenders verify your income, review your credit history, appraise the property, and ensure all legal requirements are met before funding your loan. Each stage requires specific documentation and has distinct timelines that directly affect when you can move into your new home.
Why Understanding the Application Timeline Matters
Most borrowers enter the home buying process without a clear picture of what lenders require at each stage. This knowledge gap creates unnecessary stress and can derail transactions when documents arrive late or information doesn’t match what underwriters expect.
Sellers often favor buyers who demonstrate financial readiness through organized paperwork and quick responses to lender requests. Your ability to move swiftly through each phase can mean the difference between winning a competitive bid and losing your dream property to another buyer.
Understanding the full timeline also helps you coordinate other major decisions, from giving notice at your current residence to scheduling movers and utility transfers. Financial preparation begins months before you ever submit an application, particularly if you need to address credit issues or gather complex income documentation.
Pre-Qualification Versus Pre-Approval
Pre-qualification gives you a rough estimate of how much you might borrow based on self-reported financial information. This informal assessment takes minutes and involves no credit check or document verification. While useful for initial budgeting, it carries little weight with sellers.
Pre-approval requires a full credit report, income verification, and asset documentation. Lenders issue a conditional commitment letter stating the exact loan amount you qualify for, assuming the property appraises and your financial situation remains stable. This letter demonstrates serious buyer intent and strengthens your negotiating position.
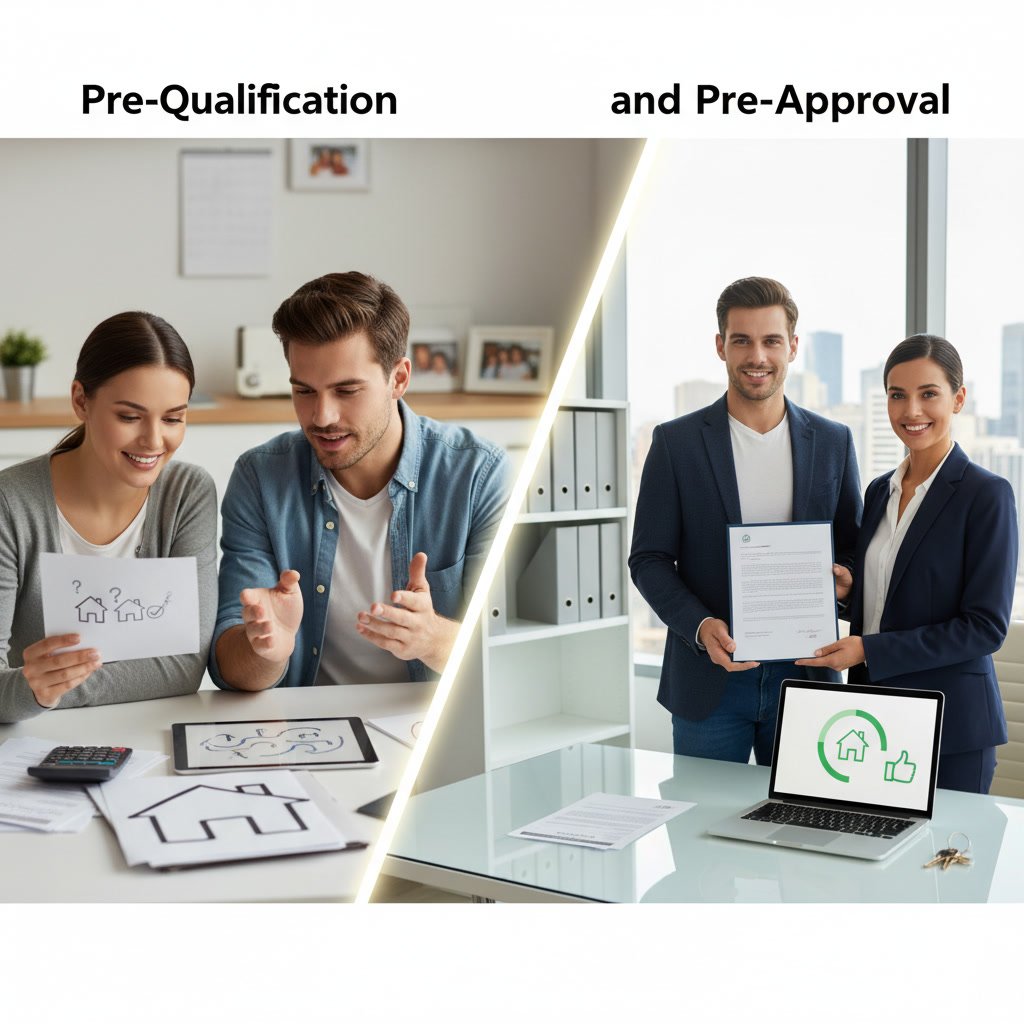
Most real estate agents won’t show properties or submit offers without a pre-approval letter in hand. The process typically takes three to five business days once you submit pay stubs, bank statements, tax returns, and employment verification.
Gathering Your Financial Documentation
Lenders require two years of tax returns, including all schedules if you’re self-employed. W-2 employees need recent pay stubs covering 30 days and W-2 forms from the past two years. Self-employed borrowers face stricter scrutiny because lenders calculate qualifying income differently than the IRS does for tax purposes.
Many business owners reduce taxable income through legitimate deductions that also reduce the income figure lenders use for qualification. If you’ve written off significant business expenses, your qualifying income may fall short of what you need to buy the home you want. Planning ahead with proper bookkeeping practices helps you balance tax strategy with borrowing capacity.
Bank statements from the past two months verify your down payment and closing cost reserves. Lenders scrutinize large deposits because they need to confirm the money comes from acceptable sources, not undisclosed loans that would affect your debt-to-income ratio. Gift funds from family members require a signed letter stating the money doesn’t need to be repaid.
The Formal Application and Initial Disclosures
Once you’ve identified a property and signed a purchase contract, you complete the formal application, known as the Uniform Residential Loan Application or Form 1003. This document captures detailed information about your employment history, income sources, assets, debts, and the property you’re purchasing.
Within three business days of receiving your application, lenders must provide a Loan Estimate that breaks down your interest rate, monthly payment, closing costs, and cash required at closing. This standardized form allows you to compare offers from multiple lenders on equal terms.
You’ll also receive initial disclosures explaining your rights, the lender’s privacy policies, and information about homeownership counseling. Review these documents carefully because the Loan Estimate locks in key loan terms and starts the clock on your rate lock period, typically 30 to 45 days.
Property Appraisal and Home Inspection in Texas
Lenders order an independent appraisal to confirm the property’s market value supports the loan amount. If you’re borrowing $300,000, the appraiser must conclude the home is worth at least that amount. Appraisals cost $400 to $600 and take one to two weeks to complete, depending on local market conditions and property complexity.
In Texas, appraisals can be particularly challenging in rapidly appreciating markets where recent comparable sales don’t reflect current buyer demand. If the appraisal comes in below your contract price, you’ll need to renegotiate with the seller, increase your down payment to cover the gap, or walk away from the deal.
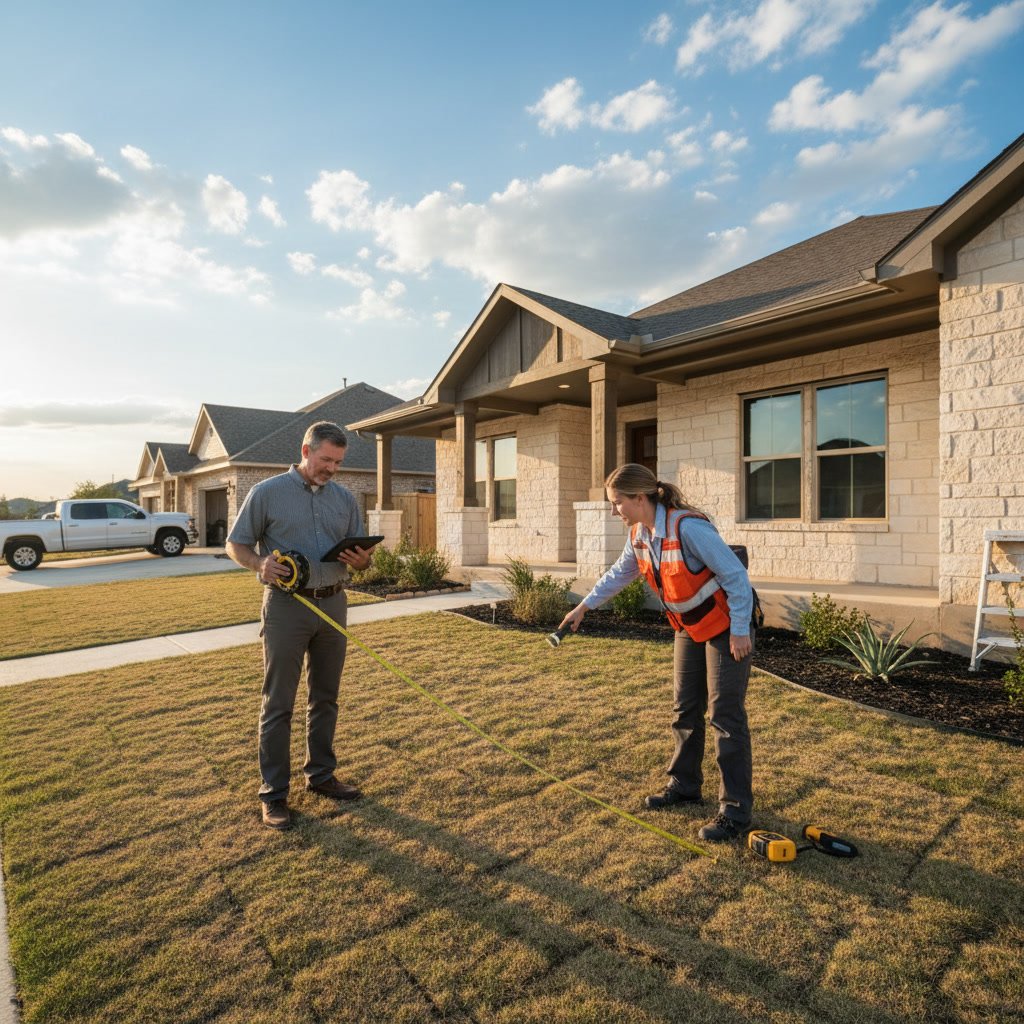
Home inspections are separate from appraisals and focus on the property’s condition rather than value. While not required by lenders, inspections protect you from discovering expensive structural, electrical, or plumbing problems after closing. Most buyers include an inspection contingency in their purchase contract, allowing them to request repairs or cancel the transaction if major issues surface.
Processing and Underwriting Review
After you submit your application and the appraisal is ordered, a loan processor verifies every piece of information you provided. They contact your employer to confirm you’re still working there and earning the stated income. They call your bank to verify account balances and review your credit report for new inquiries or accounts opened since pre-approval.
The file then moves to underwriting, where a trained specialist reviews everything against the lender’s guidelines and the investor’s requirements. Most mortgages are sold to Fannie Mae, Freddie Mac, or other investors immediately after closing, so underwriters must ensure the loan meets those entities’ strict standards.
Underwriters issue conditions, which are requests for additional documentation or explanations. Common conditions include letters explaining gaps in employment, proof that large deposits came from acceptable sources, or updated pay stubs if processing takes longer than expected. Your responsiveness to conditions directly affects your closing timeline.
Title Search and Insurance Requirements
While underwriting reviews your finances, a title company searches public records to verify the seller legally owns the property and no liens, judgments, or claims exist that could affect your ownership rights. This search uncovers unpaid property taxes, contractor liens, or previous mortgage loans that must be satisfied before the property can transfer to you.
Title insurance protects both you and your lender against future claims or defects the title search missed. Lenders require a lender’s policy covering their loan amount. Most buyers also purchase an owner’s policy protecting their equity, though this is optional in Texas.
Title issues can delay closing if the seller needs time to resolve liens or clear up ownership questions. Estates, divorces, and properties transferred through inheritance often have complicated title histories requiring legal intervention before closing can proceed.
Final Steps Before Closing Day
Three business days before closing, you’ll receive the Closing Disclosure, a final statement of your loan terms and all costs. Federal law requires this three-day waiting period so you can review the numbers and compare them to your initial Loan Estimate. Any significant changes to fees or loan terms trigger a new three-day waiting period.
During this time, you’ll also need to secure homeowners insurance and provide proof of coverage to your lender. The policy must be in effect on your closing date and list the lender as mortgagee. Shop for coverage early because some insurers require inspections or have underwriting requirements that can delay policy issuance.
Schedule a final walkthrough of the property 24 to 48 hours before closing to verify the seller completed agreed-upon repairs and the home’s condition hasn’t changed since your inspection. This is your last opportunity to identify problems before you take ownership.
The Closing Table Experience
Closing typically occurs at a title company office, attorney’s office, or lender’s office, depending on local custom and state law. You’ll sign numerous documents, including the promissory note that creates your legal obligation to repay the loan and the deed of trust or mortgage that gives the lender a security interest in the property.
Bring a government-issued photo ID and a cashier’s check or arrange a wire transfer for your down payment and closing costs. Personal checks aren’t accepted for amounts over a few hundred dollars. Your Closing Disclosure shows the exact amount you’ll need, down to the dollar.
The signing process takes 30 to 60 minutes. A closing agent or attorney explains each document before you sign, though the volume of paperwork can feel overwhelming. Don’t hesitate to ask questions about anything you don’t understand, because these documents create legally binding obligations lasting decades.
After Signing and Funding
In most states, the transaction funds and you receive keys immediately after signing. Texas uses a different process where the deed must be recorded before funding occurs, creating a brief delay between signing and actual ownership transfer. Your lender wires the loan proceeds to the title company, which then records the deed and disburses funds to the seller and other parties.
Your first mortgage payment is typically due 30 to 45 days after closing, depending on what day of the month you close. If you close on January 15, your first payment might not be due until March 1. This timing gives you breathing room to settle into your new home before the regular payment schedule begins.
Most lenders sell or transfer servicing rights to other companies within the first few months after closing. You’ll receive notice of the transfer, and your payment address will change, but the loan terms remain exactly as you agreed at closing.
Preparing Months in Advance Improves Your Outcome
The strongest mortgage applications come from borrowers who plan six to 12 months ahead. This timeline allows you to address credit issues, save additional funds for a larger down payment, and organize complex financial documentation without the pressure of an accepted offer and pending closing date.
Self-employed individuals benefit most from advance planning because they can work with financial professionals to structure their income reporting in ways that maximize both tax efficiency and borrowing power. The interplay between tax preparation strategies and mortgage qualification often requires balancing competing priorities.
Building a relationship with a loan officer before you start house hunting gives you realistic expectations about what you can afford and what documentation challenges you might face. Many borrowers discover problems during the application process that could have been resolved months earlier with proper guidance.
Working with Professionals Who Understand the Full Picture
Quick Tax and Credit Solutions Florida helps clients prepare for major financial decisions like home purchases by ensuring their tax returns, credit profiles, and business financials support their borrowing goals. The intersection of tax strategy, credit health, and mortgage qualification requires coordinated planning that most borrowers don’t consider until they’re already in contract.
Our mortgage loan services guide you through every stage of the application process, from initial financial assessment through closing day. With over 20 years of experience helping clients in Texas achieve their financial goals, we understand how to position your application for success while maintaining the tax efficiency your business needs.
If you’re planning to purchase a home in the next 6 to 12 months, start preparing now by reviewing your financial documentation, addressing credit issues, and ensuring your income reporting supports your borrowing goals. Contact Quick Tax and Credit Solutions Florida at +1 (214) 647-1669 to schedule a consultation that evaluates your complete financial picture and creates a roadmap for mortgage approval.