Credit building is a systematic process of establishing positive payment history and responsible credit use over time. Most people see measurable improvement in their credit scores within three to six months when following a structured plan, though building excellent credit typically requires 18 to 24 months of consistent positive behavior. Understanding how credit building works helps you set realistic expectations and avoid programs that promise overnight fixes.
Why Understanding the Credit Building Process Matters
Your credit score affects nearly every financial decision you make. Landlords check it before approving rental applications. Insurance companies use it to set premium rates. Employers in certain industries review credit reports during hiring. Most importantly, lenders rely on your score to determine whether you qualify for financing and at what interest rate.
People with scores below 620 often face rejection for conventional financing or pay significantly higher rates. The difference between a 620 and 720 credit score on a 30-year mortgage can mean tens of thousands of dollars in additional interest. That financial impact makes credit building one of the most valuable investments you can make in your future.
The Foundation of Credit Scores and What Drives Them
Credit scores range from 300 to 850, with most lenders using the FICO scoring model. Five factors determine your score, each weighted differently. Payment history accounts for 35 percent of your score, making it the single most important factor. Even one missed payment can drop your score by 50 to 100 points.
Credit utilization, the percentage of available credit you use, makes up 30 percent. Length of credit history contributes 15 percent, while new credit inquiries and credit mix each account for 10 percent. Professional Credit Building services focus on improving the factors with the greatest impact first.
How Professional Credit Building Services Work Step by Step
The process begins with pulling reports from all three major credit bureaus: Equifax, Experian, and TransUnion. Each bureau may show different information, so checking all three provides the complete picture. The initial review identifies negative items, errors, and opportunities for improvement.
Next comes the dispute process for inaccurate or unverifiable items. Credit bureaus must investigate disputes within 30 days and remove items they cannot verify. This step alone can produce significant score increases when reports contain errors.
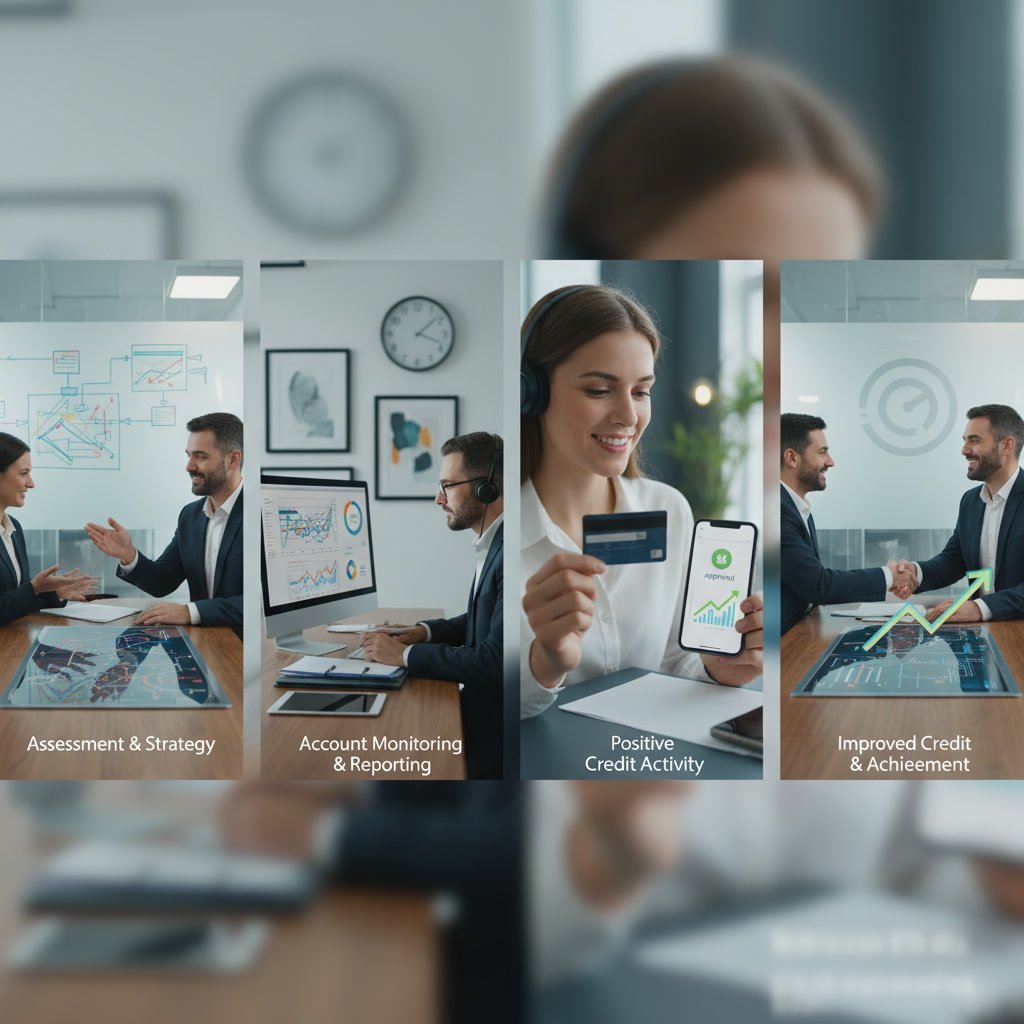
The third step involves establishing new positive trade lines. This might include secured credit cards, credit builder loans, or becoming an authorized user on someone else’s established account. Each positive account adds to your payment history and improves your credit mix.
Ongoing monitoring tracks progress and alerts you to changes. As positive payment history accumulates and negative items age off your report, scores gradually improve. Professional services adjust strategies based on what works best for your specific situation.
Realistic Timelines for Seeing Credit Score Improvements
If you have a thin file with few accounts, you can typically establish a scoreable credit profile in three to six months. Opening two secured credit cards and using them responsibly usually generates enough history for bureaus to calculate a score.
For those recovering from negative marks, timelines vary by severity. A single late payment might impact your score for 12 to 18 months but gradually loses influence. Collections accounts affect scores for up to seven years, though their impact diminishes significantly after two years.
Bankruptcies remain on reports for seven to ten years depending on the chapter filed. However, you can rebuild to a 700-plus score within two to three years after bankruptcy discharge by following a structured plan. The key is establishing new positive payment history that outweighs the old negative information.
Most people working with professional services see a 30 to 50 point increase within the first 90 days as errors get corrected and initial positive accounts begin reporting. Reaching a score above 700 typically takes 12 to 24 months of consistent effort.
Credit Building Strategies That Work in Texas
Secured credit cards are the most accessible starting point. You deposit money with the issuer, typically $200 to $500, which becomes your credit limit. Use the card for small purchases and pay the full balance each month. This establishes positive payment history without the risk of accumulating debt.
Credit builder loans work differently. The lender holds the loan amount in an account while you make payments. After completing all payments, you receive the funds. Each on-time payment builds positive history. These loans typically range from $300 to $1,000 with terms of six to 24 months.
Becoming an authorized user on a family member’s established card can boost your score quickly. You inherit the account’s positive history, though you also inherit negative marks if the primary holder misses payments. Choose this strategy carefully and only with someone who has excellent payment habits.
Common Mistakes That Slow Credit Building Progress
Closing old accounts hurts your score in two ways. It reduces your total available credit, increasing your utilization ratio. It also shortens your average account age. Keep old accounts open even if you rarely use them, assuming they have no annual fees.
Applying for multiple credit cards in a short period triggers numerous hard inquiries, each potentially lowering your score by a few points. Space out applications by at least three to six months. Too many inquiries signal financial distress to lenders.
Ignoring small collections accounts is another mistake. A $50 medical collection damages your score just as much as a $5,000 collection. Address all negative items regardless of amount. Sometimes smaller debts are easier to negotiate for deletion upon payment.
Maxing out cards, even if you pay them off monthly, temporarily spikes your utilization ratio. Credit bureaus typically receive updates once per month, and they might capture your balance on a high-utilization day. Keep balances below 30 percent of your limit, ideally below 10 percent for optimal scoring.
How Credit Building Connects to Other Financial Goals
Strong credit opens doors to better financing options across multiple areas. If you are working toward homeownership, your credit score directly affects your ability to secure Mortgage Loans with favorable terms. Most conventional mortgages require a minimum 620 score, while FHA loans may accept 580 with higher down payments.
Business owners need good personal credit to access Business Funding options. Many lenders review personal credit scores when evaluating small business loan applications, especially for newer companies without extensive business credit history. Building your personal credit simultaneously strengthens your business financing prospects.
Tax planning intersects with credit building more than most people realize. Self-employed individuals often struggle with mortgage qualification because aggressive tax deductions reduce their reported income. Understanding how lenders evaluate tax returns helps you balance deduction strategies with lending requirements, a topic covered in our post about self-employed mortgage qualification.
The Role of Credit Utilization in Your Building Strategy
Credit utilization is the second-most important scoring factor and one of the fastest to improve. This ratio compares your current balances to your total available credit across all revolving accounts. A person with $1,000 in balances and $10,000 in total limits has a 10 percent utilization ratio.
Scores respond quickly to utilization changes because bureaus update this information monthly. Paying down balances can increase your score within 30 to 45 days. Conversely, running up balances can drop your score just as quickly.
The optimal utilization rate is below 10 percent for excellent scores, though staying under 30 percent avoids major penalties. Calculate utilization both per card and across all cards combined. Some scoring models evaluate both metrics.
One expert strategy involves requesting credit limit increases on existing cards. This lowers your utilization ratio without requiring you to pay down balances. Wait at least six months after opening an account before requesting an increase, and ensure the issuer performs a soft pull rather than a hard inquiry.
When Credit Repair and Credit Building Work Together
Credit repair focuses on removing inaccurate, unverifiable, or outdated negative items from your report. Credit building establishes new positive accounts and payment history. The two strategies complement each other and produce faster results when used simultaneously.
Someone with multiple collections and charge-offs benefits from professional Credit Repair to dispute questionable items while simultaneously opening secured cards to build positive history. As negative items get removed and positive accounts mature, scores improve from both directions.
Timing matters when combining these approaches. Start credit building immediately even while disputes are in progress. The positive accounts need time to establish reporting history. Waiting until all disputes resolve wastes valuable months that could be building positive payment records.
Not all negative items can be removed through disputes. Accurate information that bureaus verify will remain on your report for its full reporting period. Credit building becomes especially important in these cases, as new positive history gradually outweighs older negative marks in scoring calculations.
Monitoring Progress and Adjusting Your Strategy
Check your credit reports from all three bureaus at least quarterly during active credit building. The federal government provides free reports through AnnualCreditReport.com, though these do not include scores. Many credit card issuers and financial apps now offer free score monitoring.
Track specific metrics beyond your overall score. Monitor the number of positive accounts reporting, your oldest account age, total credit limits, and current utilization ratio. These underlying factors tell you why your score moves up or down.
Adjust your strategy based on what moves your score most effectively. If utilization is your biggest issue, focus on paying down balances or requesting limit increases. If you lack positive payment history, prioritize opening new secured accounts. Personalized strategies produce better results than generic approaches.
Professional services provide detailed tracking and strategic adjustments you might miss on your own. They also handle the time-consuming dispute process and know which strategies work best for different situations. Quick Tax and Credit Solutions Florida has helped clients throughout Texas navigate credit building with personalized plans that account for individual circumstances and goals.
Building Credit That Opens Financial Opportunities
Credit building requires patience, consistency, and the right strategies. Most people see meaningful improvements within six months, but reaching excellent credit takes sustained effort over one to two years. The investment pays dividends through lower interest rates, better loan terms, and access to financial products that were previously unavailable.
Success comes from understanding how scores work, avoiding common mistakes, and staying consistent with positive financial behaviors. The difference between poor and excellent credit can mean hundreds of thousands of dollars over a lifetime through reduced borrowing costs and better opportunities.
Quick Tax and Credit Solutions Florida offers comprehensive credit building services designed to help you reach your financial goals faster. Our team creates personalized strategies based on your unique situation and tracks your progress every step of the way. Call +1 (214) 647-1669 to schedule a consultation and start building the credit score you need for the future you want.